Home / Builder Toolkit

Free for builders · Sheet T-11 · Guide

Lot and Construction Money

A guide for small and growing builders. Lot loans, construction loans and bridge financing: what lenders look at and how to be ready.

  • The four kinds of builder money and what each pays for
  • The five things every lender looks at
  • The project package that gets a faster answer
  • How Joe connects you with the right lending team
Get the guideT-11

It opens the moment you send this. Your project details let Joe point you to the right team.

Joe may email you about builder financing. Unsubscribe any time.

SheetT-11
FormatPDF guide
Time12-minute read
CostFree
Prepared byJoe Bogdan

A look inside

Real pages. Ready to use.

This is what lands in your inbox: a branded PDF your team can print, forward and use the same day.

Send me the guide
The cover
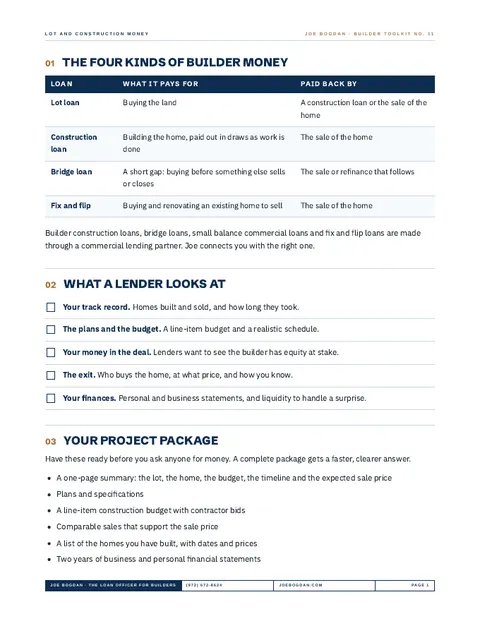
Inside
Inside

Who it is for

Small and growing builders.

If you are building your first homes or scaling from a few a year to many, this guide shows you how project money works and how to ask for it.

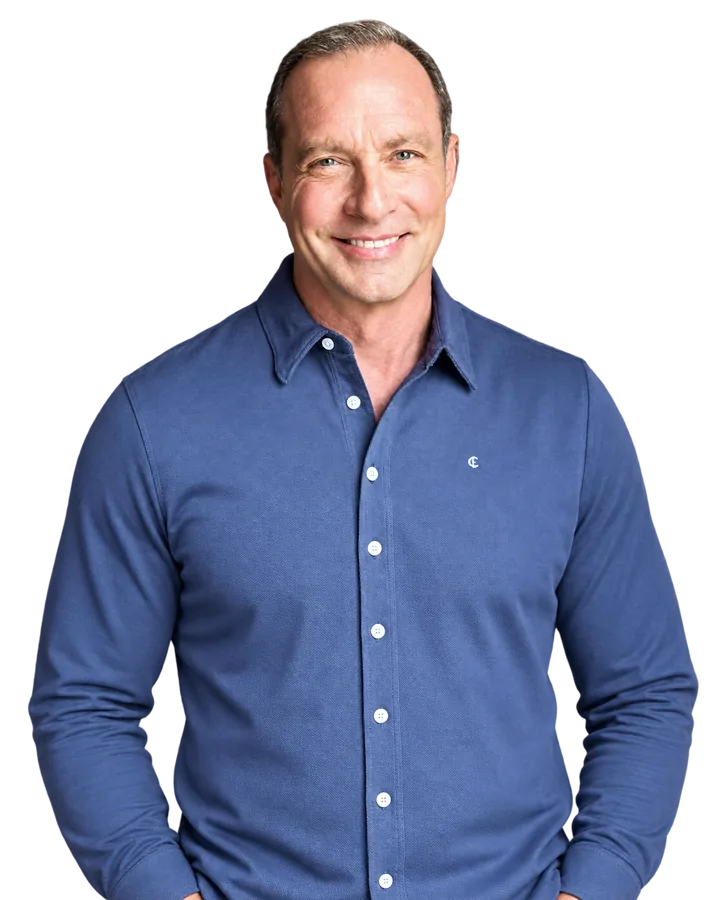
Joe Bogdan
Written by Joe BogdanSenior Loan Officer, NMLS 2795320. He works with builders only. Meet Joe

Read a sample

The first section, free and open.

No form for this part. If it is useful, the rest is one short form away.

Lot and Construction MoneyT-11

The four kinds of builder money

LoanWhat it pays forPaid back by
Lot loanBuying the landA construction loan or the sale of the home
Construction loanBuilding the home, paid out in draws as work is doneThe sale of the home
Bridge loanA short gap: buying before something else sells or closesThe sale or refinance that follows
Fix and flipBuying and renovating an existing home to sellThe sale of the home

Builder construction loans, bridge loans, small balance commercial loans and fix and flip loans are made through a commercial lending partner. Joe connects you with the right one.

What a lender looks at

  • Your track record. Homes built and sold, and how long they took.
  • The plans and the budget. A line-item budget and a realistic schedule.
  • Your money in the deal. Lenders want to see the builder has equity at stake.
  • The exit. Who buys the home, at what price, and how you know.
  • Your finances. Personal and business statements, and liquidity to handle a surprise.

Straight answers

Questions builders ask first.

All 22 answers in one free PDF →

How much of my project will the lender finance?

For qualified projects, up to 90% of cost for horizontal land development and vertical construction. That fits best when you already own the land, have paid the soft costs, and have plans, permits and bids ready to start.

Buying land and early development usually take more of your money, typically 35% to 40% down. A complete plan that covers acquisition, development and construction together may lower that by about five points.

The lender also checks value, generally 70% to 75% of the appraised value, and lends on whichever number is more conservative. You will also need cash available beyond your equity in the deal.

What can the loan budget include besides construction?

The goal is to finance the full cost of delivering the project, not only the sticks and bricks. Subject to underwriting, the budget can include:

  • Engineering and civil design
  • Architectural plans
  • Permits and other approved development costs
  • Interest reserves
  • Lender fees and closing costs
  • Other eligible soft costs tied to finishing the project
How fast can a loan close, and what will I need?

The target is about 30 days from a complete loan package, once the terms are accepted, subject to final underwriting. An incomplete package takes longer.

For a land development loan: development plans, permits and contractor bids. For a construction loan: building permits, construction plans and detailed bids. You will also provide your financial, ownership and project information. Joe will tell you what is missing and keep it moving.

Talk to Joe

Rather just talk it through?

Call Joe. One conversation, straight answers, before you sign the next contract.

Joe Bogdan, NMLS ID 2795320. CrossCountry Mortgage, LLC, NMLS ID 3029. NMLS Consumer Access. Equal Housing Opportunity. Not a commitment to lend or an offer of credit. All loans are subject to credit approval, underwriting and program guidelines. Rates, terms and programs change without notice.

© 2026 Joe Bogdan. All rights reserved.

Call Joe