Home / Builder Toolkit

Free for builders · Sheet T-12 · FAQ

The Builder Financing FAQ

Straight answers from land to keys. 22 straight answers on buyers, land, construction draws, lot releases and planning the whole project.

  • Working with Joe: buyers, closings and your current lender
  • How much the lender will finance, and how your land is counted
  • Draws, retainage and releasing lots and finished homes
  • Cost, terms, guarantees and collateral
  • Planning the whole project, from land to the final loan
Get the FAQT-12

It opens the moment you send this, and the PDF comes with it.

Joe may email you about builder financing. Unsubscribe any time.

SheetT-12
FormatPDF, 22 answers
Time15-minute read
CostFree
Prepared byJoe Bogdan

A look inside

Real pages. Ready to use.

This is what lands in your inbox: a branded PDF your team can print, forward and use the same day.

Send me the FAQ
The cover
Inside
Inside

Who it is for

Builders planning their next project.

The questions builders ask before they commit to a lender, answered plainly in one place. Read it before you sign the next contract or buy the next piece of land.

Joe Bogdan
Written by Joe BogdanSenior Loan Officer, NMLS 2795320. He works with builders only. Meet Joe

Read a sample

The first section, free and open.

No form for this part. If it is useful, the rest is one short form away.

The Builder Financing FAQT-12

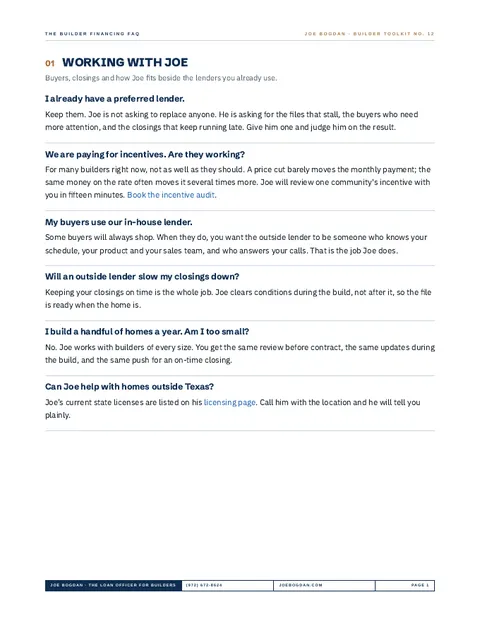
I already have a preferred lender.

Keep them. Joe is not asking to replace anyone. He is asking for the files that stall, the buyers who need more attention, and the closings that keep running late. Give him one and judge him on the result.

We are paying for incentives. Are they working?

For many builders right now, not as well as they should. A price cut barely moves the monthly payment; the same money on the rate often moves it several times more. Joe will review one community's incentive with you in fifteen minutes. Book the incentive audit.

My buyers use our in-house lender.

Some buyers will always shop. When they do, you want the outside lender to be someone who knows your schedule, your product and your sales team, and who answers your calls. That is the job Joe does.

Straight answers

Questions builders ask first.

All 22 answers in one free PDF →

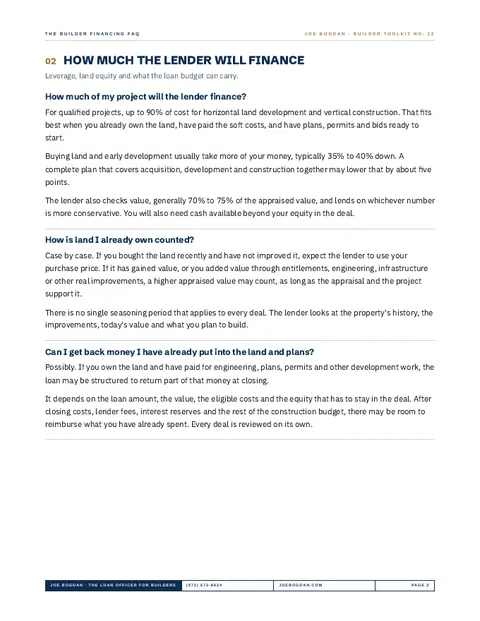
How much of my project will the lender finance?

For qualified projects, up to 90% of cost for horizontal land development and vertical construction. That fits best when you already own the land, have paid the soft costs, and have plans, permits and bids ready to start.

Buying land and early development usually take more of your money, typically 35% to 40% down. A complete plan that covers acquisition, development and construction together may lower that by about five points.

The lender also checks value, generally 70% to 75% of the appraised value, and lends on whichever number is more conservative. You will also need cash available beyond your equity in the deal.

How do construction draws work?

Draws reimburse completed work. You or your general contractor pay the subs and suppliers, then request a draw for work that is finished and verified, not for materials on order or work scheduled. Plan your working capital for the time between draws.

Plumbing, HVAC and electrical are typically reimbursed at approved stages backed by inspections and green tags. Big infrastructure, such as roads, generally has to reach its completed stage first. A complete draw package includes:

  • An itemized draw request and the invoices
  • Proof the work is complete
  • Inspection reports or green tags
  • Proof of payment
  • Lien releases

With a complete package, funding typically takes about five business days, including review and inspection. Funds go to you or your general contractor, who pays the subs.

Can one lending relationship cover the whole project?

Yes, and that is the point. The same relationship can coordinate land, development, construction and the long-term loan at the end: a rental (DSCR) loan if you keep the homes, or mortgages for your buyers if you sell them.

In return, the lending team asks to be your preferred lender and to get a real chance at that final financing. Plan the exit from day one so the construction loan and the final loan fit together. Each loan still goes through its own underwriting.
Talk to Joe

Rather just talk it through?

Call Joe. One conversation, straight answers, before you sign the next contract.

Joe Bogdan, NMLS ID 2795320. CrossCountry Mortgage, LLC, NMLS ID 3029. NMLS Consumer Access. Equal Housing Opportunity. Not a commitment to lend or an offer of credit. All loans are subject to credit approval, underwriting and program guidelines. Rates, terms and programs change without notice.

© 2026 Joe Bogdan. All rights reserved.

Call Joe